Profit rises. Cash tells another story.利润在增长,现金却走向另一边。
Apple’s FY2025 revenue rose 6.4%, net income rose 19.5%, and operating cash flow fell 5.7%. All three statements are true. An owner needs to understand why they differ before deciding what the business can sustainably distribute.Apple 2025 财年的收入增长了 6.4%,净利润增长了 19.5%,经营现金流却下降了 5.7%。三个数字都是真的。站在股东的位置,需要先解释这种差异,才能判断这门生意长期能拿出多少钱。
One idea: Turn disclosed facts into a revisable research judgment. Case · Apple FY2025 annual report and matching compensation disclosure本期知识点:把披露事实变成可以修正的研究判断。真实案例 · Apple 2025 财年年报及对应薪酬披露
This final installment combines the preceding six lessons. Open the annual report alongside this article and finish with a short, auditable research memo. Use owner economics to interpret the numbers, and competing explanations to test the business story.最后一期把前面六期合成一次完整阅读。请把年报与本文并排打开,完成一份简短、能核查的研究笔记:用所有者经济账解释数字,用替代解释检验生意判断。
Fix the document, period and accounting scope先确定文件、时间和报表范围
Open the SEC filing or the Apple investor-relations PDF. This is a fixed historical case: the Form 10-K for the fiscal year ended 27 September 2025, filed on 31 October 2025. It is not presented as the latest available report. For a new decision, you would also check subsequent annual and quarterly filings.打开 SEC 原始申报或 Apple 投资者关系页面提供的 PDF。本文固定使用一个历史案例:截至 2025 年 9 月 27 日财年的 Form 10-K,申报日为 2025 年 10 月 31 日。这里不把它称为最新年报;真正做新的判断,还要补读之后发布的年度和季度报告。
Start from the company’s investor-relations page or EDGAR, choose Form 10-K, and verify the fiscal year on the cover. A quarterly release, a shareholder presentation and a complete annual filing have different scopes. In Item 8, select the consolidated statements: these cover the parent and its consolidated subsidiaries, with intercompany effects eliminated, rather than the parent company alone. Apple explains that scope in Note 1.从公司投资者关系页面或 EDGAR 找到 Form 10-K,核对封面的财年。季度新闻稿、投资者演示文稿与完整年度申报,信息范围并不相同。在 Item 8 中读合并报表:这里包含母公司及纳入合并的子公司,并抵销内部交易影响,不是只看母公司自己的账。Apple 在附注 1 中说明了合并范围。
- Business, Item 1: what customers buy and why they return.业务,Item 1:客户买什么,为什么还会回来。
- Financial statements, pp. 29–33: record the same years and units.报表,第 29–33 页:按同一年份、同一单位摘取数字。
- Notes and management discussion: explain the movements and accounting choices.附注与管理层讨论:追查变动原因和会计口径。
- Audit, pp. 49–51: understand what was examined and the difficult judgments.审计,第 49–51 页:看审计范围,以及判断难点。
- Capital allocation: connect reinvestment, debt, dividends and repurchases.资本配置:把再投资、债务、分红与回购连起来。
Page references below use the numbers printed at the bottom of the report, not the PDF viewer’s counter. Monetary values are USD millions unless stated otherwise: 416,161 means $416.161 billion. FY2025 and FY2024 each contain 52 weeks; FY2023 contains 53. Comparisons involving FY2023 therefore include a calendar-length difference, not just business growth.下文页码按年报页脚印刷数字,不按 PDF 阅读器计数。金额除特别说明外均为百万美元:416,161 就是 4,161.61 亿美元。2025、2024 财年均为 52 周,2023 财年为 53 周。因此涉及 2023 年的比较,还包含统计时间长短的影响,不完全是经营增长。
Write the business question before the ratios先写生意问题,再算比率
A useful first sentence is: Apple sells devices and services connected to their use. The financial question is how product demand and service economics interact. The filing separates product and service revenue and costs, while its reportable operating segments are geographic. Do not call Services a separately disclosed operating segment or assume its gross profit is its operating profit.第一句话可以这样写:Apple 销售设备,也销售与设备使用相联系的服务。财务上要问的是,产品需求和服务业务的盈利能力怎样共同作用。年报分别披露产品、服务的收入与销售成本,但可报告经营分部按地理区域划分。不能把 Services 直接说成独立披露的经营分部,也不能把它的毛利当成营业利润。
Service revenue grows faster than total revenue in this case. That is a reason to examine the revenue mix, renewal behavior, distribution arrangements and regulation. It is not enough to infer durable pricing power. The business description, risk factors, Note 2 on revenue and Note 13 on segments are the next places to look. The report does not provide every retention or customer-cohort measure an owner would want.本案例中,服务收入比总收入增长更快。这提示我们继续看收入结构、续用行为、分销安排和监管影响;它本身不足以证明持久的定价权。接下来应读业务介绍、风险因素、收入附注 2 和分部附注 13。股东想知道的留存率、用户分组表现,并非都能从这份年报里找到。
Build a small ledger you can reconcile摘出一张能核对的小表
Copy a limited set of rows before calculating anything. Revenue and profit come from p. 29; operating cash, equipment spending and shareholder cash distributions come from p. 33. The final row is our calculation. Cash spending is shown below as a positive amount to subtract; it appears as an outflow in the original cash-flow statement.先摘取有限几行,再开始计算。收入与利润取自第 29 页;经营现金、设备支出、股东现金分配取自第 33 页。最后一行为本文计算值。下表把要扣除的现金支出列为正数;它在原现金流量表中以流出表示。
| Measure项目 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|
| Revenue营业收入 | 383,285 | 391,035 | 416,161 |
| Service revenue¹其中:服务收入¹ | 85,200 | 96,169 | 109,158 |
| Gross profit毛利 | 169,148 | 180,683 | 195,201 |
| Operating profit营业利润 | 114,301 | 123,216 | 133,050 |
| Net income净利润 | 96,995 | 93,736 | 112,010 |
| Operating cash, CFO经营现金流净额 CFO | 110,543 | 118,254 | 111,482 |
| Cash equipment investment²购建固定资产现金支出² | 10,959 | 9,447 | 12,715 |
| Cash share repurchases回购股票现金支出 | 77,550 | 94,949 | 90,711 |
| Cash dividends and equivalents股利及等价款现金支出 | 15,025 | 15,234 | 15,421 |
| CFO less equipment investment³CFO 减购建固定资产支出³ | 99,584 | 108,807 | 98,767 |
¹ A component of total revenue, not an additional revenue line to sum. ² Cash paid for property, plant and equipment; this is the capex proxy used throughout this example. ³ A simple, explicitly defined free-cash-flow measure, not a reported GAAP subtotal and not an estimate of maintenance-only spending.¹ 服务收入已包含在总收入中,不要再加一次。² 此处指购置不动产、厂房及设备的现金支出,全文以它作为本例的资本支出口径。³ 这里明确定义的简式自由现金流,不是报表列示的 GAAP 小计,也没有估计其中仅用于维持经营的支出。
Keep exact amounts in the working sheet and round only the displayed percentages. Comparing profit margins is division within one year; comparing growth is division across years. Mixing the two denominators is a common source of mistakes.底表保留原始金额,只对展示百分比取舍小数。算利润率是在同一年中做除法;算增长率是在两年之间做除法。把这两种分母混在一起,是常见错误。
The first result means revenue increased by about 6.43% relative to FY2024. The second means about $31.97 of operating profit for each $100 of FY2025 sales, before the items below operating profit. Neither number by itself tells us how much new capital was needed to earn it.第一个结果表示,相对于 2024 财年,收入增加约 6.43%。第二个结果表示,2025 财年每 100 美元收入形成约 31.97 美元营业利润,尚未计入营业利润以下的项目。单看其中任意一个数字,都不知道赚到它需要追加多少资本。
Explain the profit jump before extrapolating it解释利润跳升,不急着外推
Below operating profit, other income and tax expense determine net income. Note 7, pp. 40–41, identifies a large tax distortion: the State Aid Decision increased the FY2024 tax provision by 10,246, while its FY2025 reconciliation effect was −486. The FY2024 charge depressed the comparison base. This helps explain why net income growth far exceeds operating-profit growth.营业利润之后,还有其他收支和所得税费用,最终才到净利润。附注 7 第 40–41 页指出一个重要税务扰动:国家援助案相关事项使 2024 财年所得税费用增加 10,246,而 2025 财年税率调节表中该事项的影响为 −486。2024 年的费用压低了比较基数。这解释了为什么净利润增速明显高于营业利润增速。
An owner’s working conclusion is therefore narrower than “earnings power grew 19.5%.” Operations improved on these reported measures, while taxes materially affected the year-on-year net result. Removing one tax line is a sensitivity calculation, not a complete normalized-earnings estimate: other tax items, product mix and operating expenses still matter. Do not turn a comparison-base effect into a permanent growth assumption.因此,股东的工作结论应当比“赚钱能力提高了 19.5%”更谨慎:按这些披露指标看,经营有所改善,但税务事项显著影响了净利润同比。剔除一行税务项目只能作为敏感性计算,不能直接叫完整的正常化利润;其他税务因素、产品组合和经营费用仍然重要。不要把比较基数的影响,写进长期增长假设。
Follow cash through reinvestment沿着现金追到再投资
Now move from p. 29 to p. 33. FY2025 operating cash is 111,482, below FY2024’s 118,254. The reconciliation starts with net income, adds noncash adjustments, then includes movements in operating assets and liabilities. Those movements are not all customer collections or inventory: the filing’s aggregate asset and liability lines also require tax and other notes to interpret.从第 29 页走到第 33 页:2025 财年经营现金流为 111,482,低于 2024 年的 118,254。调节过程从净利润开始,加上非现金调整,再计入经营性资产、负债变动。这些变动不全是客户回款和库存;报表汇总的其他资产、负债项目,还要结合税务等附注解释。
Here 24,472 combines depreciation and amortization, share-based compensation expense and the cash-flow statement’s “Other” adjustment. The −25,000 sums its six operating-asset and liability movements. These are regrouped amounts, not extra cash-flow items to add a second time. Share-based compensation is noncash in this reconciliation, but it can dilute an owner; adding it back does not make employee compensation economically free.其中 24,472 是折旧摊销、股份支付费用与现金流量表中其他调整的合计;−25,000 是六项经营性资产和负债变动之和。这是对原表重新分组,不能再额外加一次。股份支付在这条现金调节中不直接付现,却可能稀释股东;会计上加回来,不等于员工报酬在经济上没有成本。
Where did the cash-flow growth go?多赚的利润,为什么没变成更多现金?
Inspect the underlying calculation核对完整计算底表
| Component组成 | FY2024 | FY2025 | Change变动 |
|---|---|---|---|
| Net income净利润 | 93,736 | 112,010 | +18,274 |
| Noncash adjustments非现金调整 | 20,867 | 24,472 | +3,605 |
| Operating asset/liability movements经营性资产、负债变动 | +3,651 | −25,000 | −28,651 |
| Operating cash, CFO经营现金流净额 CFO | 118,254 | 111,482 | −6,772 |
The comparison now closes: 18,274 + 3,605 − 28,651 = −6,772. Higher profit and noncash adjustments were more than offset by the swing in operating assets and liabilities. That swing identifies where to investigate; the aggregated movements alone cannot attribute the CFO decline entirely to a particular tax event.这样,同比变化也对上了:18,274 + 3,605 − 28,651 = −6,772。净利润和非现金调整增加的贡献,被经营性资产、负债变动的转向抵销。这告诉我们该去哪里追查;仅凭汇总变动,仍不能把经营现金流下降全部归因于某一税务事项。
The supplementary disclosure shows cash taxes paid of 43,369 in FY2025 versus 26,102 in FY2024; current income taxes payable also fell, as Note 6 shows. These are reasons to investigate tax-payment timing alongside operating working capital. The aggregate cash-flow lines do not establish a dollar-for-dollar allocation of the entire CFO decline to one tax event.补充披露显示,2025 年实际支付所得税现金为 43,369,2024 年为 26,102;附注 6 还显示,流动应付所得税下降。这提示我们在经营周转之外,继续追查纳税时点。仅凭现金流量表的汇总行,不能把整个经营现金流降幅逐美元归因于某一税务事件。
Simple FCF falls from 108,807 to 98,767, or 9.23%, because CFO falls and equipment spending rises. This is an observed annual cash result. Buffett’s owner-earnings question asks what spending is necessary to preserve competitive position and operating capability. The report does not split the 12,715 into maintenance and expansion. Total capex is observable; maintenance capex and sustainable owner earnings remain estimates. Review several years, business capacity and the commitments before making that estimate.简式自由现金流从 108,807 降至 98,767,下降 9.23%,原因是经营现金流减少,同时购建固定资产支出增加。这是这一年的实际现金结果。巴菲特的所有者盈余问题还要追问:维持竞争地位和经营能力,必须花掉多少?年报没有把 12,715 拆成维护性与扩张性支出。总支出可以观察;维护性支出和可持续所有者盈余仍需估计,应结合多年数据、经营能力和承诺支出判断。
See part 2 on owner earnings for the distinction. Do not subtract another full working-capital increase after starting from CFO: its operating-asset and liability adjustments are already included. Any normalization should replace a specified unusual movement with an explicit assumption, not duplicate it.这一区别见第二期的所有者盈余。以 CFO 为起点时,不要再完整扣一次营运资金增加,经营性资产、负债调整已经包含在内。若要正常化,应明确替换某项异常变动并说明假设,不能重复扣除。
Ask what cash is committed before calling it surplus先看现金承担什么义务,再说有多少富余
At the FY2025 balance-sheet date, cash plus current and noncurrent marketable securities total 132,420. Commercial paper plus the current and noncurrent carrying amounts of term debt total 98,657. The comparison is useful, but these totals do not prove that all liquidity is freely distributable. Maturity, liquidity of securities, operating needs, taxes, leases and purchase commitments must be examined together.2025 财年资产负债表日,现金及流动、非流动有价证券合计 132,420;商业票据加上流动、非流动定期债务的账面金额合计 98,657。这种对照有用,但它不能证明所有流动性都可以分给股东。还应同时检查到期时间、证券流动性、经营需要、税款、租赁和采购承诺。
Note 9, p. 44, schedules 12,393 of note principal for fiscal 2026. The balance sheet’s current term-debt carrying amount is 12,350; these differ because principal and accounting carrying value are different measures. Commercial paper is another short-term funding exposure. Notes 8–9 and the contractual-obligation discussion on p. 25 make the repayment calendar more useful than a single “debt ratio.” A manufacturing purchase commitment is also not the same thing as interest-bearing borrowing.附注 9 第 44 页列示,2026 财年到期票据本金为 12,393;资产负债表的流动定期债务账面值为 12,350。两者不同,是因为待偿本金与会计账面金额不是同一种口径。商业票据还带来另一部分短期融资需求。附注 8–9 及第 25 页合同义务说明,帮助我们排出付款时间表,比一个孤立的“负债率”更有用。制造采购承诺也不能直接等同于有息借款。
FY2025 cash repurchases plus cash dividends total 106,132, exceeding our simple FCF by 7,365. That does not by itself establish distress: the complete cash-flow statement also includes investment maturities, security sales and borrowing flows. It does establish a question: can this distribution policy continue without weakening liquidity or forgoing attractive reinvestment?2025 年现金回购加现金分红合计 106,132,比上述简式自由现金流高 7,365。这本身不等于财务困难,因为完整现金流量表还有投资到期回收、证券出售、借款等流量;它确实提出了一个问题:这种分配政策能否持续,而不削弱流动性、不放弃有吸引力的再投资机会?
Use consistent cash-flow definitions for this comparison. Note 10’s repurchase-program amount and the equity statement’s repurchase charges have different accounting scopes and need not equal the cash-flow line. For ROE, FY2025 net income divided by the simple average of FY2024 and FY2025 book equity gives about 171.4%. Long-running repurchases reduce book equity relative to a no-repurchase counterfactual, so this high ratio cannot independently establish a spectacular return on newly invested capital.做这道对照时要统一现金口径。附注 10 的回购计划金额、权益变动表中的回购记账额,与现金流量表回购流出涉及不同会计口径,不能要求三者直接相等。再看 ROE:2025 年净利润除以 2024、2025 年末账面净资产的简单平均值,约为 171.4%。相对于不回购的情况,长期回购会压低账面权益,因此这样高的比率,不能独立证明新增投入资本也获得了惊人回报。
The owner’s next question is the price paid for the shares. A buyback can increase earnings per share mechanically while destroying value if too much is paid. Buffett makes the price condition explicit in his 2022 shareholder letter. This lesson has no market-price comparison or intrinsic-value estimate, so it cannot conclude that these repurchases were attractive.股东下一步应问:公司为买回这些股份,付了什么价格?回购可以在计算上提高每股收益,却在付价过高时损害价值。巴菲特在 2022 年致股东信中明确强调了价格条件。本文没有比较市场价格与估算内在价值,因此不能据此认定这些回购划算。
Read the audit opinion for what it actually covers看懂审计意见究竟覆盖什么
Ernst & Young’s report, pp. 49–50, gives an unqualified opinion on the consolidated financial statements under US GAAP. The audit provides reasonable assurance concerning material misstatement, using evidence and judgment; it does not guarantee every number to the last dollar, endorse the business strategy or certify the stock’s value. Management remains responsible for the statements.安永在第 49–50 页对按美国 GAAP 编制的合并财务报表出具无保留意见。审计通过证据和判断,对重大错报提供合理保证;它不是保证每个数字精确到最后一美元,也不是认可经营战略或认证股票价值。管理层仍对报表负责。
The critical audit matter concerns uncertain tax positions. That is an invitation to read Note 7 carefully: a significant estimate required difficult audit judgment. A critical audit matter is not automatically a modified opinion or a finding of wrongdoing. The separate internal-control opinion has its own scope. Keep each conclusion attached to what the auditor actually examined.关键审计事项涉及不确定税务事项。这提示读者认真读附注 7:这里有重要估计,审计判断具有难度。出现关键审计事项,并不自动等于非标准意见或发现违规。另行出具的内部控制审计意见也有自己的范围。每一个结论,都应对应审计实际检查的对象。
Try three checks before opening the answers先自己做三道核查,再打开答案
Exercise 1 · Where did the margin improve?练习 1 · 利润率究竟改善了多少?
Compute operating margin for FY2024 and FY2025. Is the difference a percentage change or a percentage-point change?分别计算 2024、2025 财年的营业利润率。两者相减,单位是百分比还是百分点?
Check the reasoning核对推理
FY2024: 123,216 ÷ 391,035 = 31.51%. FY2025: 133,050 ÷ 416,161 = 31.97%. The increase is about 0.46 percentage points. Gross margin rose from 46.21% to 46.91%, while operating expenses rose from 14.70% to 14.93% of sales. The gross-margin gain more than offset the higher expense share; the next question is what drove each change.2024 年:123,216 ÷ 391,035 = 31.51%。2025 年:133,050 ÷ 416,161 = 31.97%。提高约 0.46 个百分点。毛利率从 46.21% 升至 46.91%,经营费用占收入比重则从 14.70% 升至 14.93%。毛利率的改善超过费用占比的增加;下一步才是追查这两种变化各自的原因。
Exercise 2 · How much cash was left?练习 2 · 究竟剩下多少现金?
Calculate simple FCF for FY2025, then compare it with cash buybacks plus cash dividends. Does the gap alone prove that the company borrowed to fund the entire gap?计算 2025 年简式自由现金流,再与现金回购、现金分红之和对照。差额能否单独证明公司完全靠新借款填补?
Check the reasoning核对推理
111,482 − 12,715 = 98,767. Distributions: 90,711 + 15,421 = 106,132. Difference: 7,365. No: cash is fungible and the statement includes multiple sources and uses, including securities transactions and debt repayments. A full cash reconciliation is needed before attributing funding.111,482 − 12,715 = 98,767。分配现金:90,711 + 15,421 = 106,132。差额为 7,365。不能:现金可相互调配,报表同时包含证券交易、偿还债务等多种来源与用途,要完整核对现金变动,不能只凭这个差额归因。
Exercise 3 · What cannot be copied from the filing?练习 3 · 哪个数无法直接抄出来?
Can you extract the exact amount of sustainable owner earnings from these ten rows? Name two additional judgments that would be required.能否从这十行直接摘出准确的可持续所有者盈余?说出还需要的两项判断。
Check the reasoning核对推理
No. You need an estimate of spending required to maintain competitive capacity and a view of normalized operating cash, including unusual tax/working-capital timing. The economic effect of share-based compensation and future reinvestment also matters. A transparent range with explicit assumptions is more useful than relabeling 98,767 as an exact owner-earnings figure.不能。至少需要估计维持竞争能力必须投入的支出,以及正常经营现金水平,包括异常税款、周转时点的影响。股份支付的经济影响和未来再投资同样重要。明确假设、给出范围,比把 98,767 改名为精确的所有者盈余更有用。
Finish with a one-page owner’s memo最后写一页股东研究笔记
“The size of that circle is not very important; knowing its boundaries, however, is vital.”“能力圈的大小并不很重要;知道它的边界,却至关重要。”
In this case, the cash bridge is inside what we can verify. Sustainable maintenance spending, customer retention and a defensible valuation still require evidence. A memo should preserve that boundary instead of turning a completed spreadsheet into a completed investment decision.在本案例里,现金勾稽是已经能够核查的部分;持续维持投入、客户留存和有依据的估值仍需补充证据。研究笔记应保留这条边界,不能因为表算完了,就写成投资判断也完成了。
Use six short entries. Keep facts, hypotheses and open estimates distinct; place the evidence beside the conclusion. A responsible first reading can end with “further research,” without forcing a buy or sell answer.用六项短记录完成初读。把事实、假设和待估计项分开,证据紧挨结论。一份合格的初读可以落在“继续研究”,不必强行给出买卖答案。
Fact · Cash事实 · 现金
CFO of 111,482 less equipment spending of 12,715 gives 98,767. This calculation is verified; sustainable owner earnings are not yet estimated. Source: p. 33.经营现金 111,482 减固定资产支出 12,715,得到 98,767。算术已核对,可持续所有者盈余仍待估计。来源:第 33 页。
Hypothesis · Business quality假设 · 生意质量
Services growth invites a hypothesis about continued use of the device ecosystem. The disclosure does not by itself establish retention or pricing power; compare mix, customer behavior and distribution rules.服务增长引出设备生态持续使用的假设,披露本身尚不能证明留存或定价权;继续比较结构、客户行为和分发规则。
Fact and limit · Incentives事实与边界 · 激励
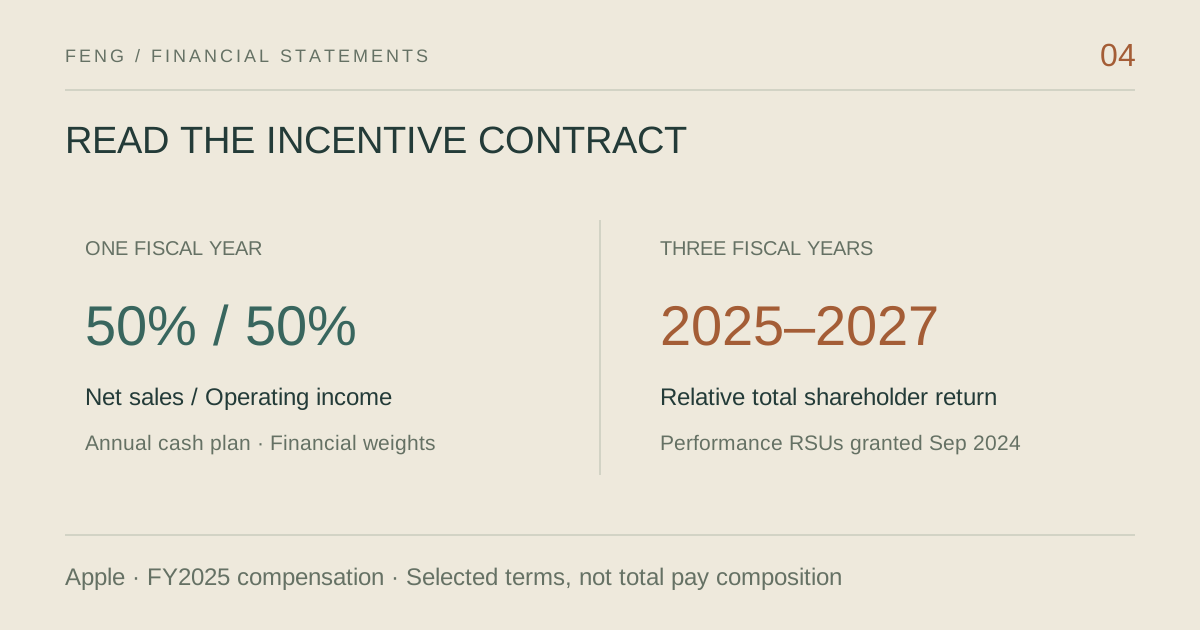
The 2026 proxy documents annual sales/operating-income incentives and multi-year relative TSR awards. Their existence does not establish why a particular capital decision was made.2026 年代理声明披露年度收入/营业利润奖励与多年相对 TSR 奖励。制度存在,尚不能证明某项资金决策的动机。
Failure test · Liquidity失败检验 · 流动性
Schedule principal, commercial paper and other obligations against usable liquidity. The annual totals do not establish the lowest cash balance during a stressed year.把本金、商业票据及其他义务与可用流动性按期对应。全年总额尚不能证明压力年份中的最低现金余额。
Open estimate · Value待估计 · 价值
Maintenance needs, normalized cash and incremental investment returns still need evidence. Without those estimates and a dated price, there is no completed purchase judgment.维持投入、正常现金与增量投资回报仍需证据。没有这些估计和对应日期的价格,就没有完成买入判断。
Revision rule · Next evidence重审条件 · 下一份证据
Revisit the thesis if customer economics weaken, capital needs rise, or distributions erode required liquidity. Specify the observation and its period before seeing the next result.客户经济性走弱、资本需求增加,或分配侵蚀必要流动性时,重审原判断。在下次结果出现前写清观察指标和期间。
Compensation source: Apple 2026 Proxy Statement, printed pp. 45–47; covering FY2025 awards.薪酬依据:Apple 2026 年代理声明第 45–47 页,覆盖 2025 财年奖励。
The method is reusable: describe the business, connect the statements, estimate owner cash, explain returns, examine incentives and liquidity, then compare value with price. For each conclusion, ask both what the numbers establish and what could make our explanation wrong.读下一家公司时仍可沿用:描述生意、连接报表、估计所有者现金、解释回报、检查激励与流动性,最后比较价值与价格。每项结论都同时回答:数字证明了什么,我们的解释又可能错在哪里。
Sources and page guide来源与查页索引
- Apple FY2025 Form 10-K · SEC original filing. Fixed case ending 27 September 2025; income pp. 29–30, balance sheet p. 31, equity p. 32, cash p. 33, policies p. 34.Apple 2025 财年 Form 10-K · SEC 原始申报。固定案例截至 2025 年 9 月 27 日;损益第 29–30 页,资产负债第 31 页,权益第 32 页,现金第 33 页,会计政策第 34 页。
- Apple-hosted annual-report PDF · business pp. 1–5; management pp. 21–26; tax pp. 40–41; leases/debt pp. 42–44; equity pp. 44–45; audit pp. 49–51.Apple 提供的年报 PDF · 业务第 1–5 页;管理层讨论第 21–26 页;税务第 40–41 页;租赁与债务第 42–44 页;权益第 44–45 页;审计第 49–51 页。
- SEC / Investor.gov · How to Read a 10-K. A guide to the report’s sections, responsibilities and disclosures.SEC / Investor.gov · 如何阅读 10-K,说明章节结构、责任与披露范围。
- SEC · Beginners’ Guide to Financial Statements. The roles of the statements, footnotes and ratios.SEC · 财务报表入门指南,解释各表、附注与比率的作用。
- Berkshire Hathaway · 1986 shareholder letter, appendix: owner earnings and the need to estimate maintenance spending.伯克希尔 · 1986 年致股东信附录:所有者盈余,以及为何必须估计维护性支出。
- Berkshire Hathaway · 2022 shareholder letter: repurchases and the price paid.伯克希尔 · 2022 年致股东信:回购与支付价格之间的关系。